October 29, 2026
Agency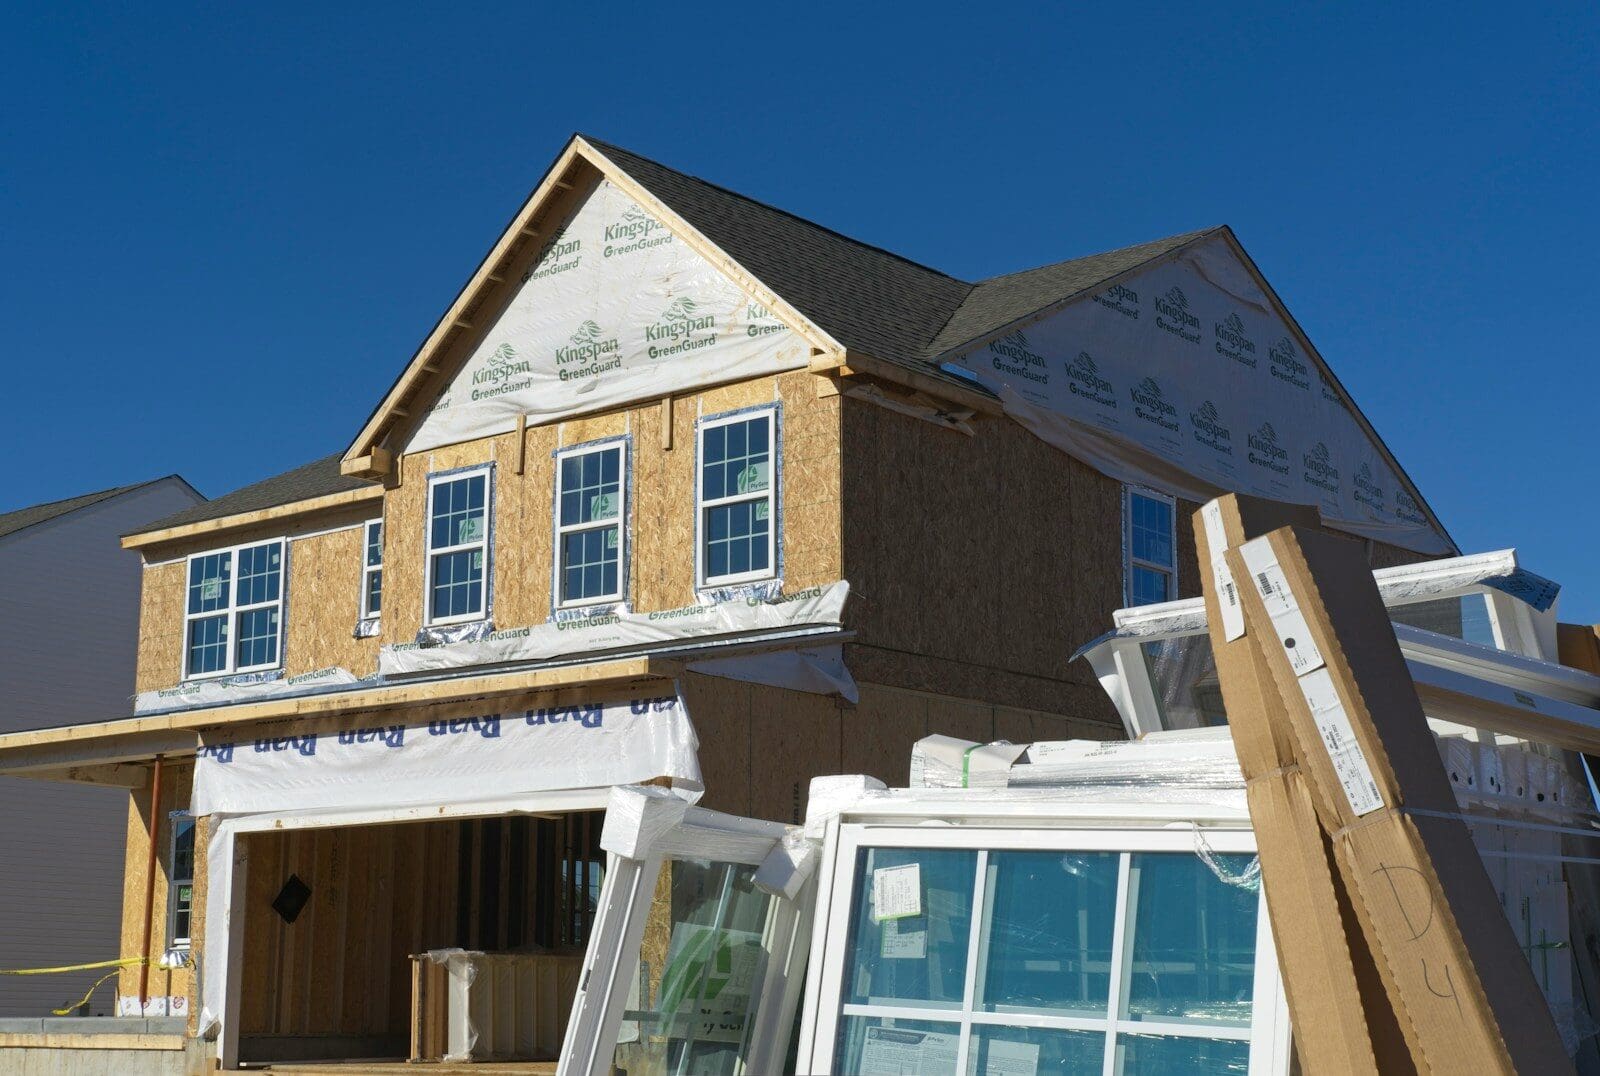
What Kind of Insurance Does a New Construction Home in Gilbert, AZ, Phoenix, AZ, Chandler, AZ Need Before Move-in Day?
Closing on a newly constructed home is an exciting milestone, and getting the right homeowners insurance in place before moving in is an essential financial responsibility. A new construction home comes without the claims history that helps buyers evaluate the risks of older properties, so working with a team that understands your situation matters.
Coverage to Have Before You Close
Once construction is complete and you close on your newly built home, a standard homeowners insurance policy becomes your primary layer of coverage. A well-structured policy typically includes:
- Dwelling coverage—May help cover the structure of the home itself
- Personal property coverage—May help cover your belongings inside the home
- Liability coverage—May help cover costs if someone is injured on your property
- Other structures coverage—May help cover detached garages, fences and outbuildings
- Loss of use coverage—May help pay for temporary living costs if the home becomes uninhabitable after a covered loss
Builders Risk Insurance and the Construction Phase
If you purchased the home before it was completed or acted as your own general contractor, builders risk insurance may have been necessary to financially protect the structure during construction. Once builders risk coverage ends, which can be triggered by occupancy of the home or policy expiration, a permanent homeowners policy needs to be in place.
What Your Lender Requires
Arizona does not legally require homeowners insurance, but mortgage lenders require coverage to be active at closing. The required coverage level is typically tied to the full replacement cost of the home.
Get Covered Before You Move In
Contact Valley Insurance Group before your closing date, so your new place has homeowners coverage prepared from day one. We proudly serve Gilbert, AZ, Phoenix, AZ, Chandler, AZ.
This blog is intended for informational and educational use only. It is not exhaustive and should not be construed as legal advice. Please contact your insurance professional for further information.
Categories: Blog